Construction Home Loans in Dallas-Fort Worth Metroplex
Building a home is a big step. Our construction home loans are designed to support you at every stage of this exciting journey.
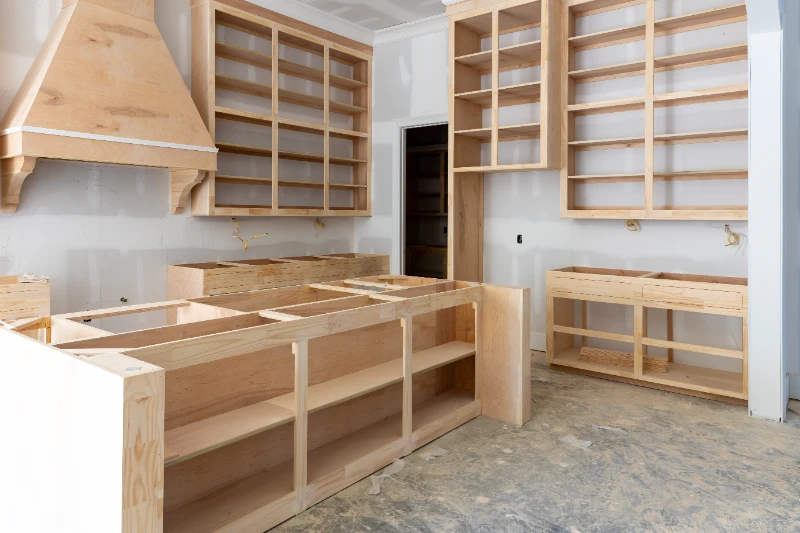
A Construction Home Loan is specialized financing designed for building a new home or completing major renovations from the ground up. For buyers and homeowners in the Dallas-Fort Worth Metroplex, Mortgage Edge provides guidance and support through every stage of the construction process, from pre-qualification to move-in. Having bought my first home as a young parent—navigating months of uncertainty even with family support—I know firsthand how critical clear communication, attention to detail, and genuine care are in making the construction loan journey smoother and more successful for our clients.
Key Takeaways
- Phased Funding: Construction Home loans release funds in stages as the project progresses, not as a lump sum at closing.
- Local Expertise: Mortgage Edge helps Dallas-Fort Worth Metroplex borrowers navigate builder approval, permitting, and draw schedules unique to our area.
- Flexible Structures: Options include construction-to-permanent, construction-only, and renovation loans, each with distinct pros and cons.
- Higher Documentation: These loans require detailed plans, budgets, builder credentials, and ongoing inspections throughout the build.
- Interest-Only Payments: During construction, you typically pay interest only on the funds drawn to date, not on the total loan amount.
- Community Commitment: As sponsors of Big Brothers and Sisters and Esperanza, we’re invested in helping our neighbors build for the future.
- Alternative Programs Available: FHA, VA, and conventional loans may be worth considering for some borrowers or project types.
Understanding Construction Home Loan Basics
Construction Home Loans in Dallas-Fort Worth Metroplex are designed for buyers who want to build a new property or undertake significant renovations rather than purchase an existing home. Unlike traditional mortgages, these loans are structured around the project’s timeline, builder qualifications, and the expected value of the finished home. At Mortgage Edge, we guide you through the complexities of construction financing, ensuring you understand each phase and requirement before you commit to your builder or plans.
Common Questions About Construction Home Loans
- What is a Construction Home Loan? It’s a short-term loan that provides financing to build a new home or renovate an existing one, with funds released in stages as construction progresses.
- Who can qualify for a Construction Home Loan? Borrowers with solid credit, verifiable income, and detailed project plans may qualify; self-employed and first-time buyers are welcome to apply, though requirements are often stricter than for standard mortgages.
- How does the draw process work? Funds are disbursed to your builder in installments after each phase of construction is completed and inspected, ensuring the project stays on track.
- Can I use a Construction Home Loan to renovate my current home? Yes, certain construction home programs allow for major renovations; see our Rehab Loan page for details.
- Is land I already own counted toward my down payment? In many cases, the equity in your land can be applied toward down payment requirements, but this depends on the specific loan program and lender guidelines.
- Do I need to use a specific builder? Most lenders require you to work with a licensed, insured, and approved builder; always confirm your builder meets lender requirements before signing a contract.
- What happens after construction is complete? The loan typically converts to a permanent mortgage, or you refinance into a new loan; see our Fixed Rate Mortgage options for more information.
- Are there alternatives to Construction Home Loans? Yes, some buyers may benefit from FHA Home Loans, VA Home Loans, or Low Down Payment Purchase Options depending on their needs and eligibility.
How Construction Home Loans Work
- Initial Consultation: We start by discussing your goals, budget, and builder plans. This early step is crucial—before you sign a contract, we help you understand what’s feasible and what documentation will be required.
- Pre-Qualification and Application: You’ll provide detailed financial information, credit history, and specifics about your builder and project. We review your income, assets, and reserves, and help you structure your application to meet lender guidelines.
- Project Review and Builder Approval: Lenders evaluate your builder’s credentials, licensing, insurance, and track record. They also review architectural plans, budgets, and construction timelines to ensure everything aligns with lending standards.
- Loan Approval and Closing: Once underwriting is complete, you close on the construction loan. For construction-to-permanent loans, this is the only closing you’ll need; for construction-only loans, a second closing is required when you transition to permanent financing.
- Draw Process and Inspections: Funds are released in phases, tied to major construction milestones (such as foundation, framing, and final finishes). After each phase, an inspection confirms completion before the next draw is approved.
- Interest-Only Payments During Construction: You make interest-only payments on the amount drawn to date, helping manage cash flow while the home is being built. Payments increase as more funds are drawn.
- Conversion to Permanent Financing: When construction is finished and the home passes final inspection, the loan converts to a permanent mortgage or is refinanced, and you begin making regular principal and interest payments.
Is a Construction Home Loan Right for You?
Construction Home Loans may be appropriate for borrowers who want to build a custom home, purchase land and build, or complete substantial renovations that go beyond cosmetic updates. This includes veterans using their VA benefits, first-time buyers with a vision for their dream home, and self-employed individuals who want more control over the building process. In our experience, these loans often work well for those who have a clear plan, a reputable builder, and the financial stability to handle the complexities and potential surprises of new construction.
However, not every borrower or project is suited for a Construction Home Loan. If you’re looking for a move-in ready property, need to close quickly, or have limited reserves for unexpected costs, traditional options like FHA Home Loans or First Time Home Buyer programs may be worth exploring. Buyers with less predictable income or those who prefer a simpler process may also want to consider alternatives such as the Bank Statement Program for self-employed borrowers.
Costs, Fees, and What to Expect
Construction Home Loans typically involve higher upfront costs, more documentation, and a longer timeline than standard mortgages. Expect to pay for two appraisals (one on plans, one on completion), periodic inspections, and potentially higher closing costs due to the complexity of the loan. Down payment requirements often start at 10-20%, though using land equity can offset this. Interest rates for construction loans are generally higher during the build phase, but may adjust or convert when you move to permanent financing.
For example, on a $600,000 construction project with 20% down, closing costs (including lender fees, title, inspections, and appraisals) can typically run $12,000–$18,000 as of 2026. Interest-only payments during construction mean your monthly obligation starts lower and increases as more funds are drawn. The full process—from application to move-in—often takes 8 to 14 months, depending on project scope and permitting.
| Feature | Construction Home Loan | Traditional Mortgage |
|---|---|---|
| Down Payment | 10-20% (land equity may apply) | 3-20% (program-dependent) |
| Closing Costs | Higher (multiple appraisals, inspections) | Lower (single appraisal) |
| Interest Rate | Higher during construction, may adjust at conversion | Typically lower, fixed or adjustable |
| Timeline | 8-14 months (from application to move-in) | 30-60 days (purchase) |
| Payment Structure | Interest-only during build | Principal & interest from day one |
We recommend reviewing all costs up front and building in a contingency reserve for unexpected expenses. If you’re comparing options, our team can help you understand how construction loans stack up against conventional and government-backed programs.
Common Mistakes to Avoid
- Choosing a builder before confirming lender approval: Not all builders meet lender requirements. We’ve seen borrowers sign contracts with family friends or unlicensed contractors, only to discover their lender won’t accept them—leading to costly delays or restarts.
- Underestimating the project budget: Construction projects often go over budget due to material costs, weather delays, or change orders. Failing to budget for a 10-15% contingency can leave you scrambling for additional funds mid-project.
- Not locking in decisions up front: Making design changes after closing (change orders) can require lender approval and may not be covered by your loan, resulting in out-of-pocket expenses and timeline setbacks.
- Missing draw schedule deadlines: If inspections or paperwork are delayed, it can halt construction and create friction with your builder. We recommend proactive communication and keeping all documentation organized.
- Assuming land value always counts as down payment: Some borrowers expect their land equity to fully cover down payment requirements, but lenders may discount value based on recent appraisals or title issues. Always verify how your specific land will be treated.
- Overlooking local permitting or HOA restrictions: In some Dallas-Fort Worth neighborhoods, permitting can take longer or require additional steps—missing these can delay your project and increase costs.
Local Considerations for Construction Home Loans in Dallas-Fort Worth Metroplex
Building in the Dallas-Fort Worth Metroplex comes with unique local requirements and opportunities. Neighborhoods like Frisco and Lakewood each have their own permitting processes, architectural guidelines, and lot availability. The area’s booming tech and healthcare sectors attract buyers seeking custom homes near major employers, while the diversity of property types—from urban infill lots in Oak Lawn to larger suburban parcels in Southlake—means construction timelines and costs can vary widely. Local municipalities may have specific rules about setbacks, energy efficiency, or floodplain construction, so it’s crucial to work with a lender and builder familiar with these dynamics. In our experience, early engagement with city or county permitting offices pays off, especially in fast-growing areas where demand for inspections and approvals can cause bottlenecks.
Ready to Explore Your Construction Home Loan Options?
At Mortgage Edge (NMLS #35960), we know firsthand how overwhelming the construction process can feel—especially for first-time buyers, veterans, or self-employed clients. Our commitment to clear communication, direct answers, and community involvement (as proud sponsors of Big Brothers and Sisters and Esperanza) means we’re here to guide you every step of the way. If you’re ready to discuss your project or want to compare construction home loans with other programs, get started with us today. We’ll help you understand your options and set realistic expectations for your build.
This is educational content and not financial advice. Loan programs and guidelines can change. Talk with a licensed mortgage professional about your specific scenario.